
Loan processor checklist: 5 file queues every mortgage brokerage should review weekly
Introduction
Are complete files sitting untouched while older applications keep moving ahead? Are missing supporting documents, lender requests, or settlement tasks only becoming visible when they turn urgent? These are signs that files enter the pipeline faster than their next actions are identified and completed. A weekly loan processor checklist makes those waiting points visible by showing where each file sits, who owns it and what must happen next.
This blog covers five queues every mortgage brokerage should review, the metrics that expose recurring bottlenecks and practical controls that can stop those queues from building up again.
Key takeaways
- Review the same five mortgage file queues every week.
- Track each file by age, owner, next action and due date.
- Separate internal delays from legitimate lender waiting time.
- Escalate missing supporting documents before they block lodgement.
- Use recurring queue patterns to identify workflow weaknesses.
Loan processor checklist for weekly file reviews
A weekly file review works best when it gives your team a clear view of what needs action now, what is waiting and what is starting to fall behind. Instead of scanning every application from start to finish, use a consistent set of checks to find files with no next action, ageing tasks, missing documents or overdue follow-ups.
This also helps separate genuine waiting time from delays caused by an unclear handover or missed task. For example, a file waiting for a lender response may be progressing within the expected timeframe, while another file marked "ready to lodge" for several days may need immediate attention.
The table below turns these checks into a simple weekly review you can apply across your pipeline:
| Weekly mortgage file health check Run this check before your weekly pipeline review |
||
|---|---|---|
| Check | What to check | What to do |
| Next step | Does every active file have a clear next step and a person responsible for completing it? | Record the next task, who will complete it and when it is due. |
| File age | Has the file been sitting at the same stage longer than expected? | Find out what is holding it up and set the next action. |
| Supporting documents | Have all requested documents been received, checked and kept up to date? | List the missing documents and follow up with the relevant person. |
| Ready to lodge | Is everything needed to prepare and lodge the application complete? | Identify what is still needed and complete it before lodgement. |
| Lender follow-up | Does every application waiting with a lender have a follow-up date? | Check the lender's expected timeframe and schedule the next follow-up. |
| Approval conditions | Does each outstanding condition have a clear task and due date? | Record each condition separately and set a date for completion. |
| Settlement | Is each approved file ready for settlement, or is there a clear reason it is still waiting? | Identify the outstanding item and act before it affects settlement. |
| Files without a clear next step | Is any file sitting in the pipeline without a clear task or person responsible for the next action? | Assign the next task and record when it needs to be completed. |
| Repeated delays | Has the same stage continued to build up for two weeks or more? | Look at why work is building up at that stage and address the underlying issue. |
What creates mortgage processing bottlenecks?
Mortgage processing bottlenecks form when the next required action is delayed. Common causes include missing documents, unclear ownership, weak handovers and unscheduled lender follow-ups.
Mortgage brokers facilitated a record 81.6% of new residential home loans in the June 2026 quarter, according to Cotality data commissioned by the MFAA. Brokers facilitated $139.08 billion in new home lending during the quarter. It is the highest lending volume recorded for any June quarter.
Higher activity creates opportunity, but it also increases the need for processing capacity that keeps files moving, according to the MFAA's latest market share data.
Moreover, the Equifax Mortgage Broker Pulse found that 80% of mortgage brokers faced significant administrative pressure, with non-integrated technology systems among the operational challenges identified.
A weekly pipeline review should therefore identify ageing, blocked and unowned files, while confirming a clear next action for every application. Reviewing the five file queues below helps pinpoint where delays occur and what needs attention first.
Are ageing files and unclear next actions slowing your team down?
Book a call to keep applications moving.

Which five file queues should a loan processor review every week?
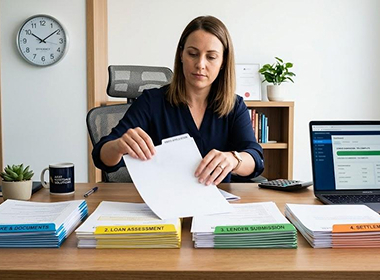
Each queue reveals a different delay. Review both the number of files in it and how long each application has remained there. Here are the following five file queues that show where applications may be slowing down and what your team should review each week.
1. Which files are waiting for supporting documents?
Record what is outstanding, when it was requested, who owns the follow-up and the next contact date. "Waiting on a client" is not enough.
Check for expired documents, fact-find inconsistencies, repeated requests without a response and missing follow-up dates. Ageing shows which supporting documents are blocking servicing, assessment or lodgement.
Ageing requests can reveal supporting documents that are delaying servicing, assessment or lodgement.
2. Which complete files are waiting for pre-lodgement review?
A complete file can still stall while waiting for checking, servicing confirmation, CRM completion, ApplyOnline preparation or lender-specific requirements.
Ask:
- How long has the file been ready?
- What exactly is preventing lodgement?
If complete files repeatedly wait for the same person, inspect the handover and approval step. This can be one of the practical virtual loan processor warning signs worth investigating.
Separate work requiring broker judgement from processing work that is simply waiting to be completed.
3. Which lodged files are waiting on lender action?
Do not place every lodged application into one generic "with lender" queue.
Record the lodgement date, the lender’s current expected turnaround, the last update and the next follow-up date. Prioritise applications that move beyond the lender’s communicated timeframe or require an outstanding action.
If the lender requests another document or clarification, assign an owner and response deadline immediately rather than leaving the file classified as "waiting on lender".
Explore our other helpful reads
4. Which conditional approvals have outstanding requirements?
"Conditional approval" is too broad to manage as one status. A file may still require a valuation, updated statement, clarification of liabilities or another lender condition.
Convert each requirement into a task with an owner and due date.
Instead of: Conditional approval
use: Valuation expected Friday. Priya to review and respond by Monday.
Clear file notes support pipeline visibility and record discipline. They can also help brokers maintain evidence of the steps taken during the credit-assistance process. ASIC’s RG 273 provides guidance on record keeping in relation to the mortgage broker best interests duty.
5. Which approved files are not yet ready to settle?
Approval is not the end of mortgage loan processing.
Check whether loan documents have been returned, settlement is booked, outstanding lender requirements are resolved, and the client knows the next action.
Keep approved applications visible until these steps are complete. A late-stage issue discovered close to settlement leaves less time for the broker, processing team and client to resolve it.
Pro tip
Track repeat queue growth by cause, not just volume, to pinpoint the workflow step creating delays.
What do recurring file queues reveal about your workflow?
A queue growing once may be an exception. Repeated growth points to a workflow weakness.
Ageing supporting documents suggest follow-up issues. Complete files waiting before lodgement point to handover delays. Lender SLAs passing unnoticed indicate weak follow-up scheduling.
When brokers repeatedly return to administration to rescue stalled files, these are among the hidden back-office support costs worth tracking.
End each weekly review with one decision: Which queue needs a workflow change this week?
How can mortgage brokerages prevent file queues from building up?
Use the following five controls to prevent repeat queues:
- Set clear entry criteria for each stage: Define what "ready" means before a file moves forward. Do not move incomplete applications into pre-lodgement review.
- Give every handover one owner: Assign one person to the next action. "Processor and broker to review" is unclear. "Processor to complete ApplyOnline by Tuesday" is measurable.
- Set ageing thresholds by queue: Set different thresholds using your service standards, lender SLAs and settlement deadlines. A pre-lodgement task should not have the same expected timeframe as lender assessment.
- Flag complex files early: Flag construction loans, unusual ownership structures and other complex applications before they enter the standard workflow. This allows additional requirements and checkpoints to be planned earlier.
- Schedule the next follow-up: Every waiting file should have a next review date, reducing unnecessary checks and exposing overdue actions. These controls turn pipeline management into an ongoing process rather than a weekly clean-up exercise.
Did you know?
A file marked "ready to lodge" can still be delayed by one missing task, document or lender requirement.
How can Brokers' BackOffice help clear recurring file queues?
Does each weekly review show files waiting before lodgement, lender requests without follow-up or approved loans with unfinished settlement actions?
Brokers' BackOffice can work within those queues.
Before lodgement, we can support document checks, CRM updates and ApplyOnline preparation. After lodgement, files can be tracked against lender progress and outstanding requirements, then followed through remaining settlement steps.
For variable volumes, Pay Per Application can support individual files as they enter the workflow. Where the same queues need ongoing ownership, a Dedicated Resource can work within the brokerage's established process. Our mortgage broker outsourcing models guide explains how the approaches differ.
Where offshore support involves personal information, privacy controls also matter. OAIC cross-border privacy guidance explains obligations that may apply when information is disclosed overseas. You can also review our Brokers' BackOffice data security controls.
Are the same files still appearing in your queue after every weekly review? Contact our team to identify where those files are stalling and which processing steps need clearer ownership, follow-up or completion.
FAQs about weekly mortgage pipeline reviews
1. Who should attend a weekly mortgage pipeline review?
Include people who can change a file's status or decide its next action, usually the broker, loan processor and operations or support lead. Smaller brokerages can run the same review with two people, provided every exception leaves the meeting with a named owner and clear deadline.
2. Should every mortgage file be discussed individually?
No. Review the pipeline at queue level first, then discuss exceptions. Prioritise ageing files, overdue actions, missing owners, lender requests, urgent settlements and applications outside expected timeframes. Files progressing normally with a clear next action do not need the same attention.
3. How should a brokerage set ageing thresholds for each queue?
Set thresholds according to what the team controls and expected external timeframes. Internal preparation may require a shorter threshold than lender assessment. Use your processing standards, current lender SLAs and settlement deadlines, then flag files that remain in one stage longer than expected.
4. How should urgent files be handled between weekly reviews?
Do not leave urgent files until the next review. Define escalation triggers for expiring approvals, settlement risks, lender requests with deadlines and missing documents that threaten lodgement. Assign the issue immediately and record who must act, what needs to happen and by when.
5. Can a small mortgage brokerage use the same five-queue system?
Yes. The framework depends on the file stage, not brokerage size. A smaller brokerage may have fewer applications in each queue, but the same controls apply: identify the stage, track how long the file has waited, assign one owner and record the next action and due date.
Final thoughts on weekly file queue review
The five-queue review makes document, pre-lodgement, lender, conditional-approval and settlement delays visible. Clear ownership, ageing thresholds and scheduled follow-ups help prevent the same queues from rebuilding.
If one queue grows every week, you know where the workflow needs attention.
Book a call with our team to identify where your loan processing files are getting stuck and keep them moving.
Table of contents
Introduction Key takeaways Loan processor checklist for weekly file reviews What creates mortgage processing bottlenecks? Which five file queues should a loan processor review every week? What do recurring file queues reveal about your workflow? How can mortgage brokerages prevent file queues from building up? How can Brokers' BackOffice help clear recurring file queues? FAQs about weekly mortgage pipeline reviews Final thoughts